With a focus on actionable insights and strategic value, The Business Research Company’s 2026 market reports include market attractiveness scoring, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, deeper supply chain intelligence, emerging startup tracking, and granular product-level insights.
Semiconductor Deposition Material Market Size Outlook: A $35.29 Billion Market By 2030, Growing At 7.5% Annually
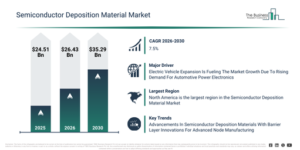
The semiconductor deposition material market has seen considerable expansion in recent years. It is projected to expand from $24.51 billion in 2025 to $26.43 billion in 2026, demonstrating a compound annual growth rate (CAGR) of 7.8%. Key factors driving this historical expansion include the growth in semiconductor manufacturing, increased utilization of ICs and memory devices, the early adoption of PVD and CVD techniques, surging consumer electronics demand, and the broader expansion of automotive electronics.
The semiconductor deposition material market is anticipated to experience substantial expansion in the coming years, reaching $35.29 billion by 2030, driven by a compound annual growth rate (CAGR) of 7.5%. This projected growth is attributed to several factors, including the emergence of advanced integrated circuit fabrication techniques, wider adoption of atomic layer deposition (ALD) for high-performance devices, expansion in power electronics and optoelectronics, rising demand from the automotive and aerospace industries, and ongoing innovations in compound semiconductor materials. Key trends during this period are expected to involve the increasing use of atomic layer deposition for creating precise thin films, a heightened demand for high-purity semiconductor deposition materials, the growing incorporation of metals, oxides, and nitrides in device manufacturing, greater integration of deposition materials in memory and power applications, and a preference for sophisticated deposition methods such as plasma-enhanced and spatial ALD.
Make Data-Driven Decisions With A Free Semiconductor Deposition Material Market Sample Report:
Key Demand Driver Expected To Lift Semiconductor Deposition Material Market Revenue
The projected growth of electric vehicles is anticipated to boost the semiconductor deposition material market throughout the forecast period. Electric vehicles are defined as automobiles powered by electric motors and battery systems, which necessitate power management integrated circuits, battery management systems, and motor control semiconductors for optimal functioning. The adoption of electric vehicles has expanded significantly due to rapidly decreasing battery prices, making EVs more affordable and encouraging more consumers to transition from conventional fuel-based cars. Semiconductor deposition materials play a vital role in electric vehicles by enabling the manufacture of high-performance power electronics and control chips that optimize battery management, charging efficiency, and overall vehicle performance. For instance, in May 2025, the International Energy Agency, a France-based intergovernmental organization, reported that global EV sales surpassed 4 million, reflecting a 35% increase compared to the same period in 2024. The agency also projects that over 20 million new electric cars will be sold by the end of 2025, a 25% year-on-year increase from the 17 million EVs sold in 2024. Thus, the increasing expansion of electric vehicles is propelling the semiconductor deposition material market.
Exploring The Semiconductor Deposition Material Market Through Its Key Segments
The semiconductor deposition material market covered in this report is segmented –
1) By Type: Physical Vapor Deposition (PVD), Chemical Vapor Deposition (CVD), Atomic Layer Deposition (ALD), Electrochemical Deposition
2) By Material Composition: Metals, Oxides, Nitrides, Polymer-Based Materials, Silicon-Based Materials, Compound Semiconductors
3) By Deposition Technique: Chemical Vapor Deposition, Physical Vapor Deposition, Atomic Layer Deposition, Other Deposition Techniques
4) By Application: Integrated Circuits (ICs), Memory Devices, Power Devices, Optoelectronic Devices, Light Emitting Diodes And Laser Diodes, Semiconductor Packaging
5) By End-Use Industry: Consumer Electronics, Telecommunications, Aerospace And Defense, Automotive, Healthcare, Industrial Automation
Subsegments:
1) By Physical Vapor Deposition (PVD): Sputtering, Evaporation, Cathodic Arc Deposition, Pulsed Laser Deposition, Molecular Beam Epitaxy
2) By Chemical Vapor Deposition (CVD): Plasma Enhanced Chemical Vapor Deposition, Low Pressure Chemical Vapor Deposition, Atmospheric Pressure Chemical Vapor Deposition, Metal Organic Chemical Vapor Deposition, Atomic Layer Deposition
3) By Atomic Layer Deposition (ALD): Thermal Atomic Layer Deposition, Plasma-Enhanced Atomic Layer Deposition, Spatial Atomic Layer Deposition, Thermal Spatial Atomic Layer Deposition, Radical-Enhanced Atomic Layer Deposition
4) By Electrochemical Deposition: Copper, Nickel, Gold, Silver, Cobalt, Platinum, Palladium, Ruthenium, Rhodium, Alloy
New Trends Redefining Competition In The Semiconductor Deposition Material Market
Leading companies in the semiconductor deposition material market are prioritizing innovations in barrier materials, focusing on the development of advanced barrier layers with significantly enhanced barrier characteristics for extreme ultraviolet (EUV) lithography and next-generation chip architectures. These sophisticated materials are engineered to provide superior protection against moisture, oxygen, and chemical contamination, ensuring the structural integrity and performance of ultra-thin device layers at nanoscale dimensions. For example, in May 2023, Merck KGaA, a Germany-based leading science and technology company, introduced a new series of advanced barrier materials specifically for semiconductor applications. These materials are designed to offer outstanding impermeability, which allows for thinner film stacks without compromising reliability, thereby supporting the industry’s transition to sub-3 nm nodes and advanced 3D device structures. This innovation improves process uniformity, film adhesion, and long-term device stability, leading to a significant increase in yield rates for logic and memory manufacturers. Furthermore, these barrier materials are fully compatible with existing chemical vapor deposition (CVD) and atomic layer deposition (ALD) tools, facilitating their seamless integration into current semiconductor fabrication workflows.
Semiconductor Deposition Material Market Competition: Key Players And Industry Participants
Major companies operating in the semiconductor deposition material market are Shin-Etsu Chemical Co. Ltd., Merck KGaA, JSR Corporation, Fujifilm Electronic Materials Co. Ltd., Dow Inc., Entegris Inc., Air Products and Chemicals Inc., Air Liquide S.A., Linde plc, SK Materials Co. Ltd., Evonik Industries AG, Wacker Chemie AG, Mitsubishi Chemical Corporation, ADEKA Corporation, Tanaka Kikinzoku Group, Materion Corporation, Soulbrain Co. Ltd., Kanto Chemical Co. Inc., Honeywell International Inc., Plansee Group, Cabot Microelectronics Corporation, and Sumitomo Chemical Co. Ltd.
Get The Detailed Semiconductor Deposition Material Market Research Report Here:
Semiconductor Deposition Material Market Regional Overview: Largest Market And Global Coverage
North America was the largest region in the semiconductor deposition material market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the semiconductor deposition material market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.
Reach Out To Our Team:
The Business Research Company: https://www.thebusinessresearchcompany.com/
Americas: +1 310-496-7795
Asia: +44 7882 955267 & +91 8897263534
Europe: +44 7882 955267
Email us at: marketing@tbrc.info
Follow us on:
LinkedIn: https://in.linkedin.com/company/the-business-research-company
YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ
Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model

Wasay has over a decade of experience in market research, data modelling, and analytics, with prior experience at GlobalData and Decision Tree Consulting Services. At The Business Research Company , he leads research operations across syndicated studies, customized consulting engagements, and the Global Market Model platform. His professional experience includes supporting organizations such as Boston Consulting Group, KPMG, and Ernst & Young. Wasay holds a degree in Electronics and Communications Engineering, postgraduate management qualifications from International Management Institute Belgium and Indian School of Business and Entrepreneurship, and completed the Integrated Program in Business Analytics from Indian Institute of Management Indore.