With a focus on actionable insights and strategic value, The Business Research Company’s 2026 market reports include market attractiveness scoring, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, deeper supply chain intelligence, emerging startup tracking, and granular product-level insights.
Rapid Prototyping In Aerospace And Defense Market Size Snapshot: 2026 Valuation, 2030 Projection And Key Growth Factors
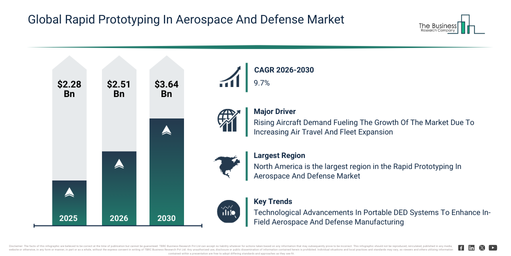
The rapid prototyping in aerospace and defense market size has experienced significant expansion over recent years. This market is projected to expand from $2.28 billion in 2025 to $2.51 billion in 2026, demonstrating a compound annual growth rate (CAGR) of 10.1%. The historical increase in this market can be attributed to several factors, including the increasing integration of 3D printing and additive manufacturing for quick aerospace component development, a heightened need for design validation models to speed up aircraft and spacecraft testing, the early incorporation of wind tunnel scale prototypes to enhance aerodynamic performance, an increase in reverse engineering services for older defense platforms, and the growing utilization of low-volume pre-production runs to reduce development timelines in defense programs.
The rapid prototyping in aerospace and defense market is anticipated to experience robust expansion over the coming years. Its size is projected to reach $3.64 billion by 2030, exhibiting a compound annual growth rate (CAGR) of 9.7%. This growth during the forecast period is driven by several factors, including an increased demand for digital twin simulation to enhance prototype performance and lower redesign expenses, the growing uptake of rapid tooling customization for quicker manufacturing shifts, the expanding application of additive manufacturing for structural components of unmanned aerial vehicles, the broadening of accelerated failure testing services to certify advanced aerospace materials, and the progression of prototyping technologies facilitating quicker production of intricate thermal shielding and high-precision defense parts. Key trends anticipated within this period involve a heightened demand for rapid tooling and low-volume production, greater adoption of high-temperature materials for hypersonic prototyping, an increase in reverse engineering services for older defense platforms, expanded use of wind tunnel scale models for aerodynamic assessment, and the creation of thermal shielding prototypes designed for spacecraft reentry systems.
Get A No-Cost Sample Of The Rapid Prototyping In Aerospace And Defense Market Study:
Major Factor Fueling The Rapid Prototyping In Aerospace And Defense Market Through 2030
The growing requirement for aircraft is anticipated to fuel the expansion of the rapid prototyping for aerospace and defense market in the future. An aircraft encompasses any device or vehicle capable of flight, including airplanes, helicopters, and drones. This surge in aircraft demand stems from increased air travel, as more individuals opt for flights for both business and leisure purposes. The convenience of flying has been enhanced by affordable ticket prices and improved airport infrastructure, compelling airlines to enlarge their fleets. Consequently, aircraft manufacturers leverage rapid prototyping to efficiently design, test, and refine aerospace and defense components, thereby reducing development timelines and costs. For instance, in May 2025, Airbus SE, a France-based commercial aircraft manufacturer, reported that commercial aircraft deliveries in 2024 increased by 4% compared to 2023, with 766 aircraft delivered, a rise from 735 the previous year. Furthermore, total commercial aircraft orders reached 2,094 in 2024, marking a substantial increase from 820 orders in 2023. Therefore, the heightened demand for aircraft is a key driver for the rapid prototyping for aerospace and defense market.
Rapid Prototyping In Aerospace And Defense Market Segment Landscape: Main Categories And Subcategories Covered
The rapid prototyping in aerospace and defense market covered in this report is segmented –
1) By Type: Stereolithography Apparatus (SLA), Laminated Object Manufacturing (LOM), Selective Laser Sintering (SLS), Three Dimension Printing (3DP), Fused Deposition Modeling (FDM)
2) By Technology: 3D Printing, Computer-Aided Design (CAD), Computer Numerical Control (CNC) Machining, Additive Manufacturing, Hybrid Manufacturing Techniques
3) By Application: Aircraft Manufacturing, Missile Systems, Spacecraft Development, Defense Systems, Aerospace Component Manufacturing
4) By End-User: Military Organizations, Civil Aviation Authorities, Aerospace Research Institutions, Private Aerospace Companies, Government Defense Contractors
Subsegments:
1) By Stereolithography Apparatus (SLA): Desktop Stereolithography Apparatus (SLA) Printers, Industrial Stereolithography Apparatus (SLA) Printers, Resin-Based Materials, Aerospace Component Mockups
2) By Laminated Object Manufacturing (LOM): Paper-Based Laminated Object Manufacturing (LOM), Plastic-Based Laminated Object Manufacturing (LOM), Metal Foil-Based Laminated Object Manufacturing (LOM), Low-Cost Prototyping Applications
3) By Selective Laser Sintering (SLS): Nylon Selective Laser Sintering (SLS), Metal Selective Laser Sintering (SLS), Composite Selective Laser Sintering (SLS), Functional Testing Parts
4) By Three Dimension Printing (3DP): Binder Jetting, Material Jetting, Powder Bed Printing, Concept Models And Wind Tunnel Prototypes
5) By Fused Deposition Modeling (FDM): Desktop Fused Deposition Modeling (FDM) Printers, Industrial Fused Deposition Modeling (FDM) Printers, Thermoplastic Filament Materials, Tooling And End-Use Part Prototypes
How Are Emerging Trends Influencing The Rapid Prototyping In Aerospace And Defense Market’s Growth Path?
Key companies operating in the rapid prototyping for aerospace and defense market are prioritizing the development of technological advancements like portable directed energy deposition (DED) systems to enable in-field, on-demand metal manufacturing and repairs. These portable DED systems employ laser or electron energy to fuse metal wire or powder directly onto surfaces, facilitating high-precision component production or repair in remote locations. For example, in February 2025, ADDiTEC Technologies Ltd., a US-based industrial 3D printing company, unveiled the AMDROiD X. This system incorporates a self-contained modular container with integrated power (solar-rechargeable batteries), multi-axis robotic motion control, and an optional 12 kW fiber laser, allowing up to 4 kg/hr metal deposition for fast repair and manufacturing of aerospace and defense components in austere environments. It improves deployment readiness by providing autonomous metal 3D printing capabilities directly at forward operating bases or mission-critical sites.
Rapid Prototyping In Aerospace And Defense Market Leading Players And Key Industry Participants In 2026
Major companies operating in the rapid prototyping in aerospace and defense market are The Boeing Company, Lockheed Martin Corporation, Airbus SE, Northrop Grumman Corporation, GE Aerospace, Renishaw plc, Stratasys Ltd., 3D Systems Corporation, Proto Labs Inc., Materialise NV, Nikon SLM Solutions Group AG, ExOne Company, Ultimaker BV, Hoganas AB, Nano Dimension Ltd., VoxelJet AG, EOS GmbH, AON3D Inc., Sciaky Inc., CRP Technology S.r.l.
Check Out The Full Rapid Prototyping In Aerospace And Defense Market Report 2026:
Rapid Prototyping In Aerospace And Defense Market By Geography: Revenue Leaders Among Global Regions
North America was the largest region in the rapid prototyping in aerospace and defense market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the rapid prototyping in aerospace and defense market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.
Reach Out To Our Team:
The Business Research Company: https://www.thebusinessresearchcompany.com/
Americas: +1 310-496-7795
Asia: +44 7882 955267 & +91 8897263534
Europe: +44 7882 955267
Email us at: marketing@tbrc.info
Follow us on:
LinkedIn: https://in.linkedin.com/company/the-business-research-company
YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ
Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model

Wasay has over a decade of experience in market research, data modelling, and analytics, with prior experience at GlobalData and Decision Tree Consulting Services. At The Business Research Company , he leads research operations across syndicated studies, customized consulting engagements, and the Global Market Model platform. His professional experience includes supporting organizations such as Boston Consulting Group, KPMG, and Ernst & Young. Wasay holds a degree in Electronics and Communications Engineering, postgraduate management qualifications from International Management Institute Belgium and Indian School of Business and Entrepreneurship, and completed the Integrated Program in Business Analytics from Indian Institute of Management Indore.